THE PROTEIN PULSE - Monday Market Open | October 12th, 2026
Oct 12, 2026 · 9 min · 10 segments
# THE PROTEIN PULSE ## Monday Market Open | October 12th, 2026 ## Full Executive Briefing — Spoken Script **HOST:** Welcome to The Protein Pulse Podcast, your daily market update on all things…
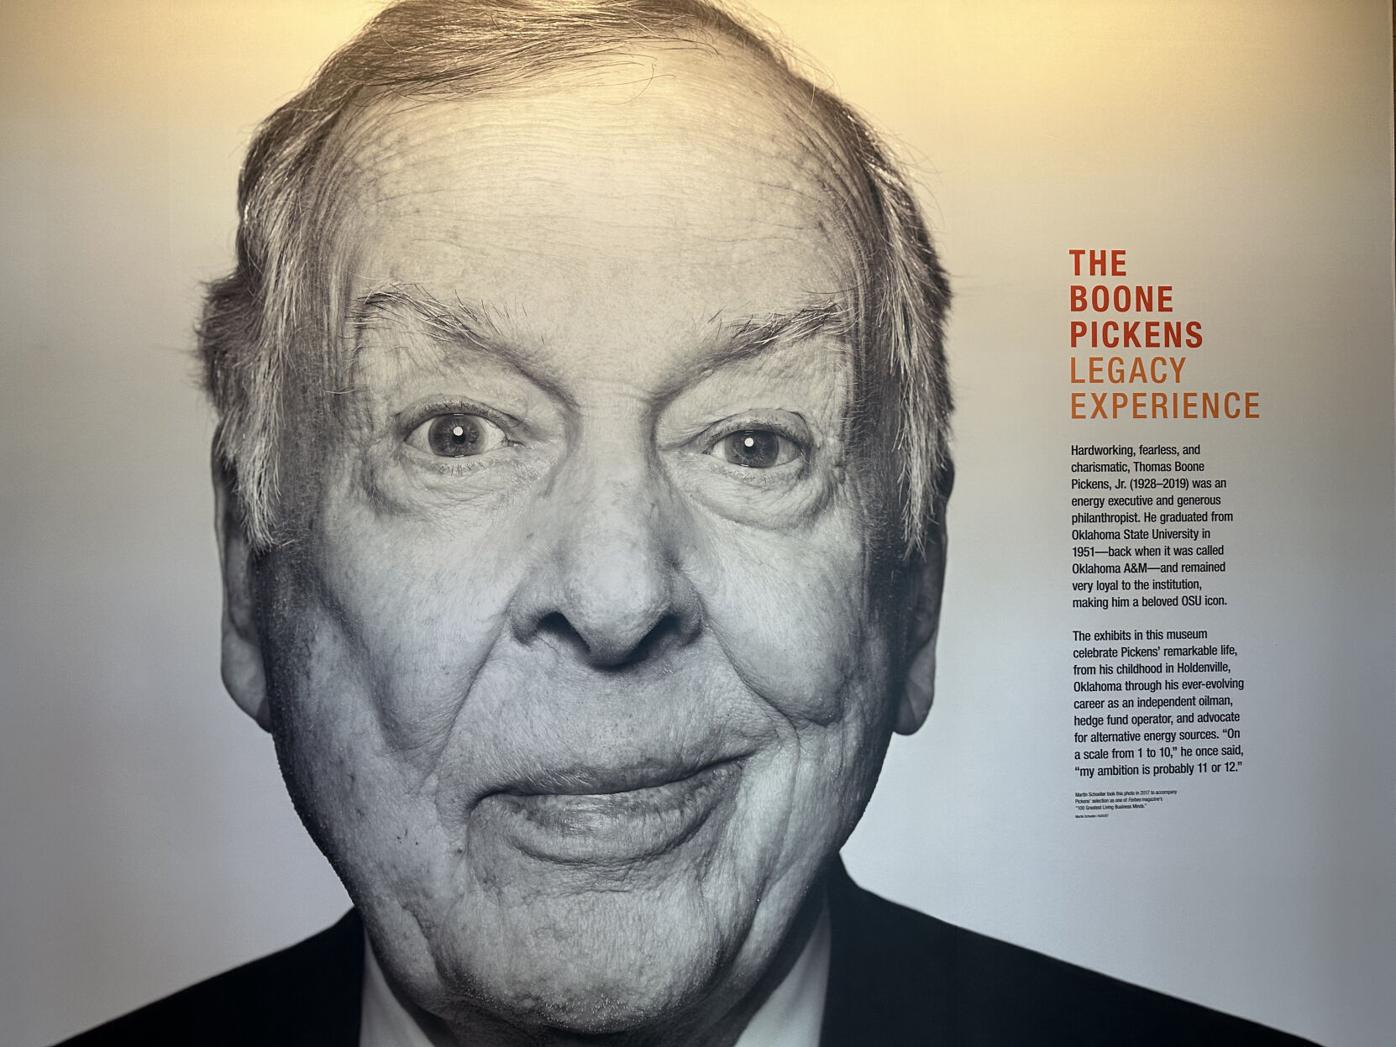
# THE PROTEIN PULSE ## Monday Market Open | October 12th, 2026 ## Full Executive Briefing — Spoken Script **HOST:** Welcome to The Protein Pulse Podcast, your daily market update on all things protein. This is Monday Market Open for October 12th, 2026, from The Sparks Group. **SHAWN:** John Tyson got a laugh this week when asked why he couldn't bankroll Arkansas football like Cody Campbell, the Texas Tech oilman and major Red Raiders booster. "He's got oil, and I've got chickens." As a die-hard Oklahoma State Cowboy, that one hit home. We had our own oilman in T. Boone Pickens, and I sure wish he were still around. We've endured some lean years since Boone's passing, so seeing the Pokes back in the Top 25 makes this one a little sweeter. College football has become big business. NIL, transfer portals, and multimillion-dollar rosters have changed the game. But spending money and building something sustainable aren't necessarily the same thing. The protein industry understands that lesson. Capital opens doors, but margins, discipline, and execution determine who stays competitive. Boone understood the value of investing in something you believe in. Money can build a program. Commitment builds a legacy. Go Pokes. **HOST:** Friday's October Wasdy reset the grain outlook. Corn futures fell sharply while feeder cattle rallied, but the protein supply equation remains uneven. Cattle availability is constrained, pork weakened on a weekly basis, and broiler production is forecast to expand. The margin challenge differs by protein. Tight cattle supplies favor producers while restricting packer utilization. Pork depends increasingly on export markets, and chicken must balance production growth with profitable demand. For buyers, the opportunity is understanding where those economic pressures create leverage, and where they don't. **SHAWN:** Friday's Choice cutout declined a dollar fifty to three seventy-three thirty-five. Select gained two fifty-seven to three fifty-four thirty. The Choice Select spread narrowed to nineteen oh five. Heavy boneless Choice ribeyes averaged fifteen eighty-one. Meanwhile, eighty-one percent ground beef averaged three forty-seven seventy-two. Daily fresh nineties were three ninety-six ninety-two. Fresh fifties were ninety-four twelve. The weekly fresh nineties average was three ninety-eight eighty. Premium middle meats and grinding components are not moving as one market. Different specifications create different buying opportunities. Weekly cattle slaughter totaled an estimated five hundred thirty-one thousand head, down three point seven percent. Year-to-date slaughter reached twenty-one point oh eight eight million, down seven point four percent. Projected 2026 beef production was reduced seventy-five million pounds to twenty-four point eight oh two billion. December live cattle settled Friday at two twenty-seven, up three fifty. November feeders gained seven oh seven five to three forty-one ninety-five. Expensive cattle and underutilized packing capacity continue to squeeze processing economics. An important distinction: the frequently cited eighty-five percent Big Four concentration figure applies to fed-cattle processing, not all cattle slaughter. The markets for fed cattle and cull cows differ significantly in processing economics, products and procurement competition. That distinction matters when evaluating consolidation, packer margins and competition for available cattle. Mexican feeder cattle entering through Douglas totaled a reported twenty-four thousand six hundred fifty since August 24th, versus twenty-five thousand three hundred fifty during the comparable 2024 period. Expanded lean-beef import access also has yet to deliver noticeable retail price relief. Approximately thirty-seven thousand four hundred eighty-six metric tons entered under the new tariff-rate quota through September 28th, against a one hundred thousand ton first-month allowance. Not all those imports represent additional supply beyond normal trade, and retail pricing does not respond immediately to raw-material changes. Separate fed beef, cow beef and imported grinding inputs. Expanded access does not guarantee cheaper delivered beef. **HOST:** Projected 2026 broiler production increased one hundred million pounds to forty-nine point seven two billion. For October 5th through 9th, boneless skinless breasts averaged one eighteen. Tenderloins one thirteen fifty. Whole wings one ten sixty. Boneless skinless thighs one sixty-eight. All four increased modestly. Drumsticks eased to fifty-three cents. Bulk leg quarters averaged fifty-three cents. Higher production forecasts do not guarantee lower wholesale prices across every cut. Proposed processing line-speed limits could rise from one hundred forty to one hundred seventy-five birds per minute, but physical infrastructure remains a constraint. One industry estimate suggests faster line speeds could add only zero to half a percentage point to annual chicken-production growth over the next three years. Additional poultry housing and processing investment would still be required. JBS is pursuing higher-value prepared proteins. Its Just Bare chicken brand surpassed a company-reported one billion dollars in annual retail sales, while a four hundred million dollar Georgia investment targets additional prepared-food capacity. Sausage and bacon investments in Iowa extend that strategy into pork. The opportunity is not simply producing more protein. It is capturing more value through convenience, branding and product differentiation. Negotiate commodity chicken independently of prepared-food growth. Additional capacity and profitable supply expansion are not the same thing. **SHAWN:** Friday's daily pork cutout gained eighty-six cents to eighty fifty. Bellies increased six eighty-one to eighty-nine twenty-seven, while hams rose forty-six cents to sixty-nine twenty-nine. The five-day cutout averaged eighty-two thirty-four, down three seventy-two from the preceding week. Hams averaged seventy-two oh four, down nine fifty-six. Bellies averaged ninety seventy-seven, down three eighty-four. Friday's recovery did not reverse the weaker weekly trend. Estimated weekly hog slaughter reached two point six two seven million head, up one point eight percent. Projected 2026 pork production was reduced one hundred fifty million pounds to twenty-seven point six two one billion. December lean hogs settled Friday at sixty-seven eighty-three, down seventy-eight cents. August pork exports totaled a reported two hundred twenty-two thousand two hundred forty-three metric tons, down six percent, while value fell twelve percent to six hundred six million dollars. When domestic demand fails to absorb available production, export markets become more important to processor margins. But export weakness does not affect every primal equally. Evaluate ham, belly and trim commitments separately. Softer weekly values create opportunities, but Friday's rebound warrants discipline. **HOST:** October Wasdy raised projected corn yield from one hundred seventy-eight point five to one hundred eighty-one point two bushels an acre. Production climbed two hundred thirty-four million bushels to sixteen point oh three four billion, while projected ending stocks increased two hundred eighty-two million to one point eight four nine billion. December corn settled Friday at four eighty, down twenty and a half cents. December soybean meal moved the opposite direction, gaining eight dollars to three sixty-five sixty. Projected soybean production increased to four point five six two billion bushels, with ending stocks at three hundred fifteen million. Corn's decline improves potential feed economics, but ration costs still depend on meal, cash basis, freight and existing coverage. Reprice corn exposure against delivered ration costs before assuming improved finished-protein economics. CONAB reports October 15th. The next Wasdy is November 10th. New World screwworm surveillance remains central to Mexican cattle movements. Reopened crossings have not restored unrestricted feeder access. HPAI was confirmed in two Washington dairy herds. Biosecurity vigilance remains important, although no commercial meat-supply disruption has been established from those detections. For protein buyers, the immediate concern is operational continuity. Border restrictions, animal-health controls and livestock availability remain interconnected procurement risks. **SHAWN:** What I'm watching. Corn's response to Friday's Wasdy selloff. Monday's cattle and hog futures. The divergence between premium beef and grinding inputs. Whether pork's late-week recovery holds. Also whether expanded beef import access produces measurable wholesale or retail price relief, and how quickly chicken processors can translate investment into actual production. Procurement radar. Beef: price fed beef, cow beef and grinding components independently. Monitor imported lean availability and packer utilization. Chicken: compare cuts individually. Do not price in line-speed gains before physical capacity expands. Pork: evaluate ham and belly coverage against export exposure and the weaker weekly market. Feed: reassess corn coverage using delivered ration economics, not futures alone. Friday changed the grain balance sheet, not the protein supply equation. Expensive cattle and underused packing capacity challenge beef margins. Pork needs stronger demand to absorb production. Chicken's path runs through disciplined capacity growth and higher-value products. Buy each protein against its supply, demand and margin pressures, not a single feed-cost signal. Lower input costs create possibilities. They don't guarantee lower purchase prices. Stay disciplined. **HOST:** That's The Protein Pulse, Monday Market Open for October 12th. From Shawn Sparks and The Sparks Group. **SHAWN:** Stay disciplined.
# THE PROTEIN PULSE ## Monday Market Open | October 12th, 2026 ## Full Executive Briefing — Spoken Script **HOST:** Welcome to The Protein Pulse Podcast, your daily market update on all things…