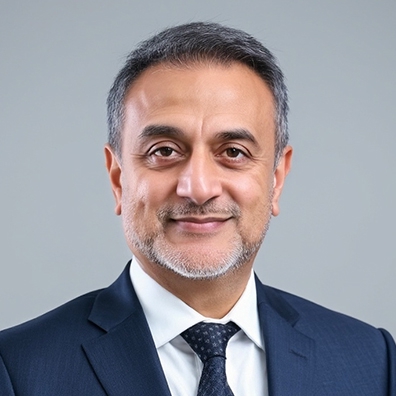
Dharmesh Mistry
Fintech commentator and co-host of the Dave and Dharm Demystify podcast; CEO of Vision 20 20 Consulting and author of The Intelligent Ledger.
3
APPEARANCES
3
PODCASTS
Oct 15, 2026


Dharmesh MistryGUEST
Look, let me and this is where it's not to talk about my career, but this is where the benefit of hindsight really comes in.
Dharmesh MistryGUEST
When I first started in technology in the bank, I'd already been writing games for PCs and also had been learning my craft originally on terminal access to a mainframe from the college.
Dharmesh MistryGUEST
But when I first started at the bank, I was working on one of the very first releases of the IBM 1390 mainframe, right? Which at the time cost about 4 million, right? Plus, depending on the add-ons that you took.
Dharmesh MistryGUEST
And I remember the PC coming out and thinking, wow, like before you need to have 4 million quid.
5 MINS LATER

Efi PylarinouHOST
What are those forces? And what is the concept that you have developed around this?


Theodora LauHOST
Why five? Why not 10 years? Why not give yourself a little bit longer leeway? What exactly is the things that, you know, banks need to do and decide by then why?
Dharmesh MistryGUEST
Look, the answer to that is all in the book, which I urge everyone to read, because it's quite complicated.
Dharmesh MistryGUEST
But once you understand it, you just kind of think, oh, suddenly you can see this jigsaw has come together, right? Because without it, the pieces are all happening independently.
Dharmesh MistryGUEST
It's like, as Lewis said, is that the convergence actually comes to something different, right? So banks have been very good at adopting individual technologies.
Dharmesh MistryGUEST
So if I look at the past, the shift from mainframe to PCs and client server, the shift towards the internet, the shift towards mobile, the shift towards cloud, cloud native, right? None of those have actually created a disruptive event in banking, in which case we might as well say, well, there's been no disruption in banking for decades, right? However, we have seen disruption elsewhere and specifically like the smartphone.
Dharmesh MistryGUEST
So if you look at the smartphone, what actually happened was that, you know, you had Nokia busily making a better phone, right? And the iPhone came along and it was a better phone, but it was also a better camera and a GPS device and a thousand other applications in the app store, right? That had better bandwidth, et cetera.
7 MINS LATER

Lou CarlozoGUEST
And I think once you get the person who is the visionary and can understand this, it's game over.

Dharmesh MistryGUEST
One is that, look, if I go through the technologies, then, you know, the only one that kind of questions the date whether it will happen within the five years was quantum.
Dharmesh MistryGUEST
But even quantum, this time last year, people were saying you have to be QSA by 2035 at the earliest.
Dharmesh MistryGUEST
But within the space of us writing the book, that estimate has dropped from 2035 to 2030, which actually means that banks need to be working on their QSA programs now.
15 MINS LATER
Dave WallaceHOST
And I think because you can't apply the same rules that you've applied all along to this, can you, Dharmesh?