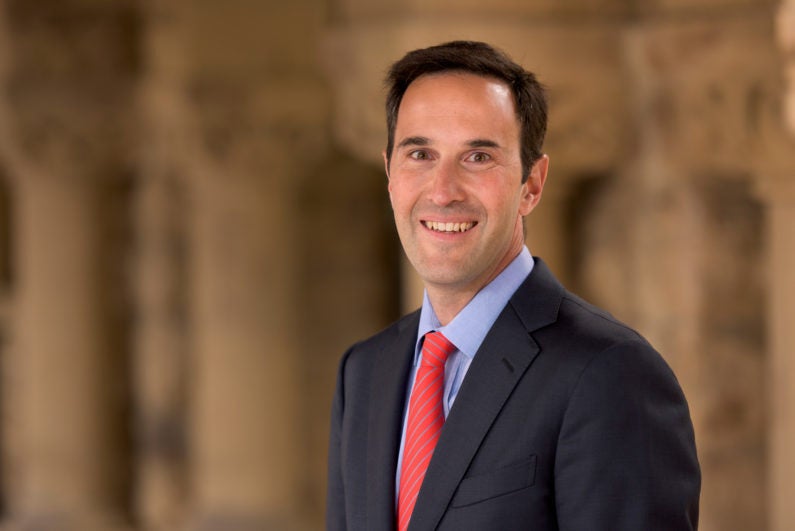
Jonathan Levin
President of Stanford University
18
APPEARANCES
10
PODCASTS
Oct 16, 2026


Jonathan LevinGUEST
Las tasas ya estaban muy bajas después de los choques del 11 de septiembre y todo, y el banco central realmente no podría bajar mucho más la tasa de interés, pero los bonos no estaban respondiendo.
Jonathan LevinGUEST
Así que la Reserva Federal empieza a caer bajo la influencia de Michael Woodford y empieza a explorar cómo pueden manipular las expectativas de los mercados y de los hogares para conseguir sus objetivos.
Jonathan LevinGUEST
Y fue en ese entonces que Alan Greenspan, apenas meses después de un documento, una publicación muy importante de Michael Woodford, Greenspan sale con un comunicado revolucionario diciendo básicamente: las tasas de interés se van a quedar donde están por un buen rato.
Jonathan LevinGUEST
Y eso sí ayudó, aunque sea brevemente, a bajar las tasas de interés, los yields de los bonos a diez años, por ejemplo, que son tan fundamentales para las hipotecas en Estados Unidos y muchos otros tipos de bonos.

Eduardo ThompsonHOST
Y con la Fed de ahora, ¿cuál es la justificación de Kevin Warsh para comunicar menos? ¿Y hay algo que se pueda rescatar de esa estrategia?
Jonathan LevinGUEST
estrategia?Lo que pasa con Warsh es que él está respondiendo de la experiencia de 2021 y la Fed de Jerome Powell en ese entonces estaba usando bastante forward guidance, como le llaman, para efectivamente bajar los yields de los bonos durante la pandemia.

Ed LudlowHOST
intelligenceW- w- w- the Microsoft part of this, why, why is it that Napster needs to go through Microsoft and Azure to do this? Explain the deal essentially.
Jonathan LevinGUEST
Well, I mean, in essence, uh, there are many companies that are partners obviously with, uh, Microsoft.
Jonathan LevinGUEST
And, uh, we saw an opportunity to sort of continue to sit and work with all the large language models with our, uh, with our agent.
Jonathan LevinGUEST
And, uh, quite frankly, Microsoft was the best partner, uh, for us at this point to really make sure that our customers own the data, own th- own their own customers, own their experience, um, uh, and really own their models, and I think that's the path that we saw Microsoft on.
Jonathan LevinGUEST
Our agents, uh, uh, uh, sit on top of all models, so we're really, uh, quite frankly, um, um, the interface, um, what, what c- our customers would use to have an interface with a customer.
Jonathan LevinGUEST
Um, and so it, it's super important, uh, that we keep our, our focus on how our customers can have the best interaction with their customers, uh, and really pivot the discussion away from cutting costs and how AI displaces folks and really sort of pivoting the conversation to how we can learn through these online interactions, for example, why 90% of people aren't buying from your website, and start to figure out how AI can be a tool to the blue sky side of the equation.


Ray BriggsHOST
The modern theory of utility makes no attempt to explain choice behavior." So John, what exactly is utility and why does it matter? [chuckles]

Jonathan LevinGUEST
You're asking, Rae, that you're, you're getting into a very deep problem in, in economics, which is why do people make certain choices? That's the foundation of, you know, really all of economics and the foundation of game theory, 'cause game theory you're in a strategic setting, you gotta decide, uh, what to do and, um, what are your motivations.
Jonathan LevinGUEST
When I taught first year economics, I, you know, I always would, would try to talk to people about the sort of caricature version of economics where you sort of specify a, a, a preference as utility function that's very material.
10 MINS LATER


Jonathan LevinGUEST
Yeah, uh, the point of my column, uh, on Greenspan is, is like, look, it's obviously very tempting to draw parallels between AI and the internet era.
Jonathan LevinGUEST
And of course, Greenspan's famous call in the late '90s was, uh, letting the economy sort of, sort of run because, uh, he thought, you know, incipient productivity was so strong, we, you know, we didn't have to worry too much about inflation.
Jonathan LevinGUEST
My argument is, is that beyond those ostensible similarities, there are a lot of differences.
Jonathan LevinGUEST
So, uh, you know, take for instance, the fact that, uh, you know, Greenspan had demographics on, on his side, the great moderation.
Jonathan LevinGUEST
Uh, he, uh, you know, enjoyed a long period of relatively low and stable energy prices.
Jonathan LevinGUEST
Obviously, that's not at all similar [laughs] uh, to the world we're living in today.


Paola Vega TorreCORRESPONDENT
Jon, después de tanto entusiasmo, ¿cómo interpretamos la volatilidad de las acciones de SpaceX?
Jonathan LevinGUEST
Lo que pasó en los últimos quince años deja claro que los mega IPO no suelen ser tan buena inversión.
Jonathan LevinGUEST
Generan tanto entusiasmo y salen a bolsa con valuaciones tan disparatadas que muchas veces ni siquiera le ganan al S&P 500 en los primeros uno a tres años.
Jonathan LevinGUEST
Primero, ya le estás agregando un montón de deuda a la estructura de capital.


Jonathan LevinGUEST
We'll have some questions from, uh, from students, and, uh, l- looking forward to, to hearing your thoughts.
Jonathan LevinGUEST
Um, maybe we would-- You've been chronicled a lot recently, a movie, a, a, a book.
14 MINS LATER

Jonathan LevinGUEST
But now look at those pension funds, institutional wealth managers, the institutional financial endowments and funds that exist throughout the world, as well as family offices and high net worth individuals.
Jonathan LevinGUEST
These are folks that are investing generationally in the land and have seen it produce over time.
PhilAUDIENCE
Yeah.

Jonathan LevinGUEST
But now look at those pension funds, institutional wealth managers, the investors.
Jonathan LevinGUEST
the institutional financial endowments and funds that exist throughout the world, as well as family offices and high net worth individuals.
Jonathan LevinGUEST
Lo que digo en mi columna de esta semana es que obviamente es una empresa impresionante.
Jonathan LevinGUEST
O sea, la tecnología que tienen en términos de lanzar satélites y llegar a nuevos planetas.
Jonathan LevinGUEST
Y yo digo que eventualmente vas a querer tener esta compañía en tu portafolio.


Greg MatuskyHOST
Why don't you quickly just share your story? How, how did you, uh, co-found Chainalysis?
Jonathan LevinGUEST
Yeah, I, I really fell into crypto, and actually, you know, I'm maybe a couple of hundred meters from when I first really got my break in cryptocurrency.
Jonathan LevinGUEST
I was, uh, sitting at the Yerba Buena Center right next door to Moscone, and I was speaking about cryptocurrency in 2014 at the first CoinSummit conference.
Jonathan LevinGUEST
I was researching, I was writing the early game theory work and empirical work on how does-... blockchain work as a payment system? How can it be that we can have this decentralized money system that's a public good? And from there, I realized as I was looking at that data, there needed to be someone who actually understands how and why people are using cryptocurrency if this is ever gonna be a big market.
Jonathan LevinGUEST
And I met my co-founders at Chainalysis, who were just starting to actually investigate the same type of problem.
Jonathan LevinGUEST
And the three of us got together and we said, "You know, we need to be the people that create this map between the real world and the blockchain transactions." And it just happened to be that the first use case for that was criminal investigations that involved cryptocurrency that was stolen from other people, or being used on the dark web to facilitate, you know, drug trafficking or, or child exploitation.
Greg MatuskyHOST
So where does it go from here? Uh, particularly with quantum computing on the horizon and-


Kristen LeemanGUEST
And then the second part is we actually had some, uh, local families who, uh, some of whose kids, all of who had been counseled on tracheostomy, some of whose kids ended up with a tracheostomy tube, and then, uh, another one who, who did not ex- uh, go through their experience as well.
Jonathan LevinGUEST
It was really cool because the audience was like a focus group, so we asked them about cases, and there was a lot of variability in their opinions on whether they would recommend, how likely they were to recommend tracheostomy at different time points.
Jonathan LevinGUEST
And so we wanted to get a, a sense of, you know, with this baseline information, what is the current state across the nation for, um, counseling.
Jonathan LevinGUEST
And then when you add on different comorbidities, like if you have pulmonary hypertension, how does that change your conversation? How does that change your counseling?
speaker_0ADVERTISER
Mm-hmm
Jonathan LevinGUEST
But if you are in a place that doesn't have those, it was gonna require ongoing hospitalization, then you may give the patient more time.
Jonathan LevinGUEST
But what came up over and over again was the family being a huge partner in all of this.
Eduardo ThompsonHOST
¿Pero son realmente oportunidades únicas o una señal de advertencia? Hoy conversamos con Jonathan Levin, columnista de Bloomberg Opinion, sobre qué dice la historia y los datos acerca de estos momentos de euforia financiera.
Jonathan LevinGUEST
Los retornos más extraordinarios ya se ganaron antes del primer día de cotización en muchos de estos gran IPOs de la última década.
Jonathan LevinGUEST
Todo el mundo está muy emocionado por estas tres ofertas públicas que vienen tal vez este año.
Jonathan LevinGUEST
Y la verdad es que las valuaciones ya han subido bastante en los mercados privados.
Eduardo ThompsonHOST
Acá nos dice por qué nunca estuvo del todo convencido de que el Sell America duraría.
Jonathan LevinGUEST
Hay que empezar con qué es la narrativa de que los inversionistas estaban vendiendo a Estados Unidos.
Jonathan LevinGUEST
Y esta narrativa surge como una manera de explicar la caída coordinada de los activos estadounidenses al principio del gobierno de Trump.
Jonathan LevinGUEST
Y desde entonces nadie ha dejado de hablar de esta narrativa que le llaman el Sell America Trade en inglés.
Jonathan LevinGUEST
¿Por qué? Bueno, para empezar, en las últimas dos semanas, el mundo ha sufrido un shock en forma de la guerra en Irán.
Paola Vega TorreCORRESPONDENT
¿En realidad han ayudado a bajar los precios y reducir el déficit comercial o han generado nuevos problemas?
Jonathan LevinGUEST
Así que técnicamente eso parece ser un poco mejor, pero hay que considerar el contrafactual.
Jonathan LevinGUEST
Walsh empezó su carrera en la política monetaria en 2006 y estaba en la Reserva Federal cuando se desató la crisis financiera.
Jonathan LevinGUEST
Y bajo Ben Bernanke, la Reserva Federal empezó una política de comprar bonos en el mercado abierto para tener influencia sobre toda la curva.
Jonathan LevinGUEST
Y en ese tiempo, Bush estaba constantemente preocupado que íbamos a desatar una nueva ronda de inflación.
Eduardo ThompsonHOST
¿Cuál es la lectura que haces de los últimos datos y el rumbo de tasas de interés?
Jonathan LevinGUEST
Este año los estrategas de Wall Street están más o menos optimistas en comparación con años pasados.
Jonathan LevinGUEST
El problema es que la historia demuestra que estas predicciones no son nada fiables, lamentablemente.
Jonathan LevinGUEST
O sea, en ocho de los últimos nueve años, estas predicciones han tenido un margen de error de doble dígitos.


Tony EdwardHOST
I don't know if you can share details some you know, but as much as you can, what are some of the common scams that you're seeing that people are trying to do?
Jonathan LevinGUEST
I would say that one that we're very familiar with is the investment scams that are popping up.
Jonathan LevinGUEST
We screen really every single website that is created in the world every day.
17 MINS LATER
speaker_1ADVERTISER
Varies by state.

4:49

How are these policies affecting the labour market right now? Or what's the concern for local employers?
Jonathan LevinGUEST
Yeah, well, a labor market, it's not exactly clear just yet, but I think we're seeing indications of this in the housing market.
Jonathan LevinGUEST
For instance, people are more apprehensive about making long term decisions because they don't know what their status is going to be in the medium term.
Jonathan LevinGUEST
Over the next few months, you have to start feeling the impacts because estimates from the likes of Morgan Stanley suggest that the net flows of immigrants, this is both documented and undocumented, are going to step down in just a huge way from 2024 to 2025.
Jonathan LevinGUEST
The estimate is that we'll go from something on the order of a net 3 million all the way down to something on the order of a 0.3, 0.4 million.
Jonathan LevinGUEST
And it's something that's going to feel even more massive in immigrant heavy cities like the one that I live in.