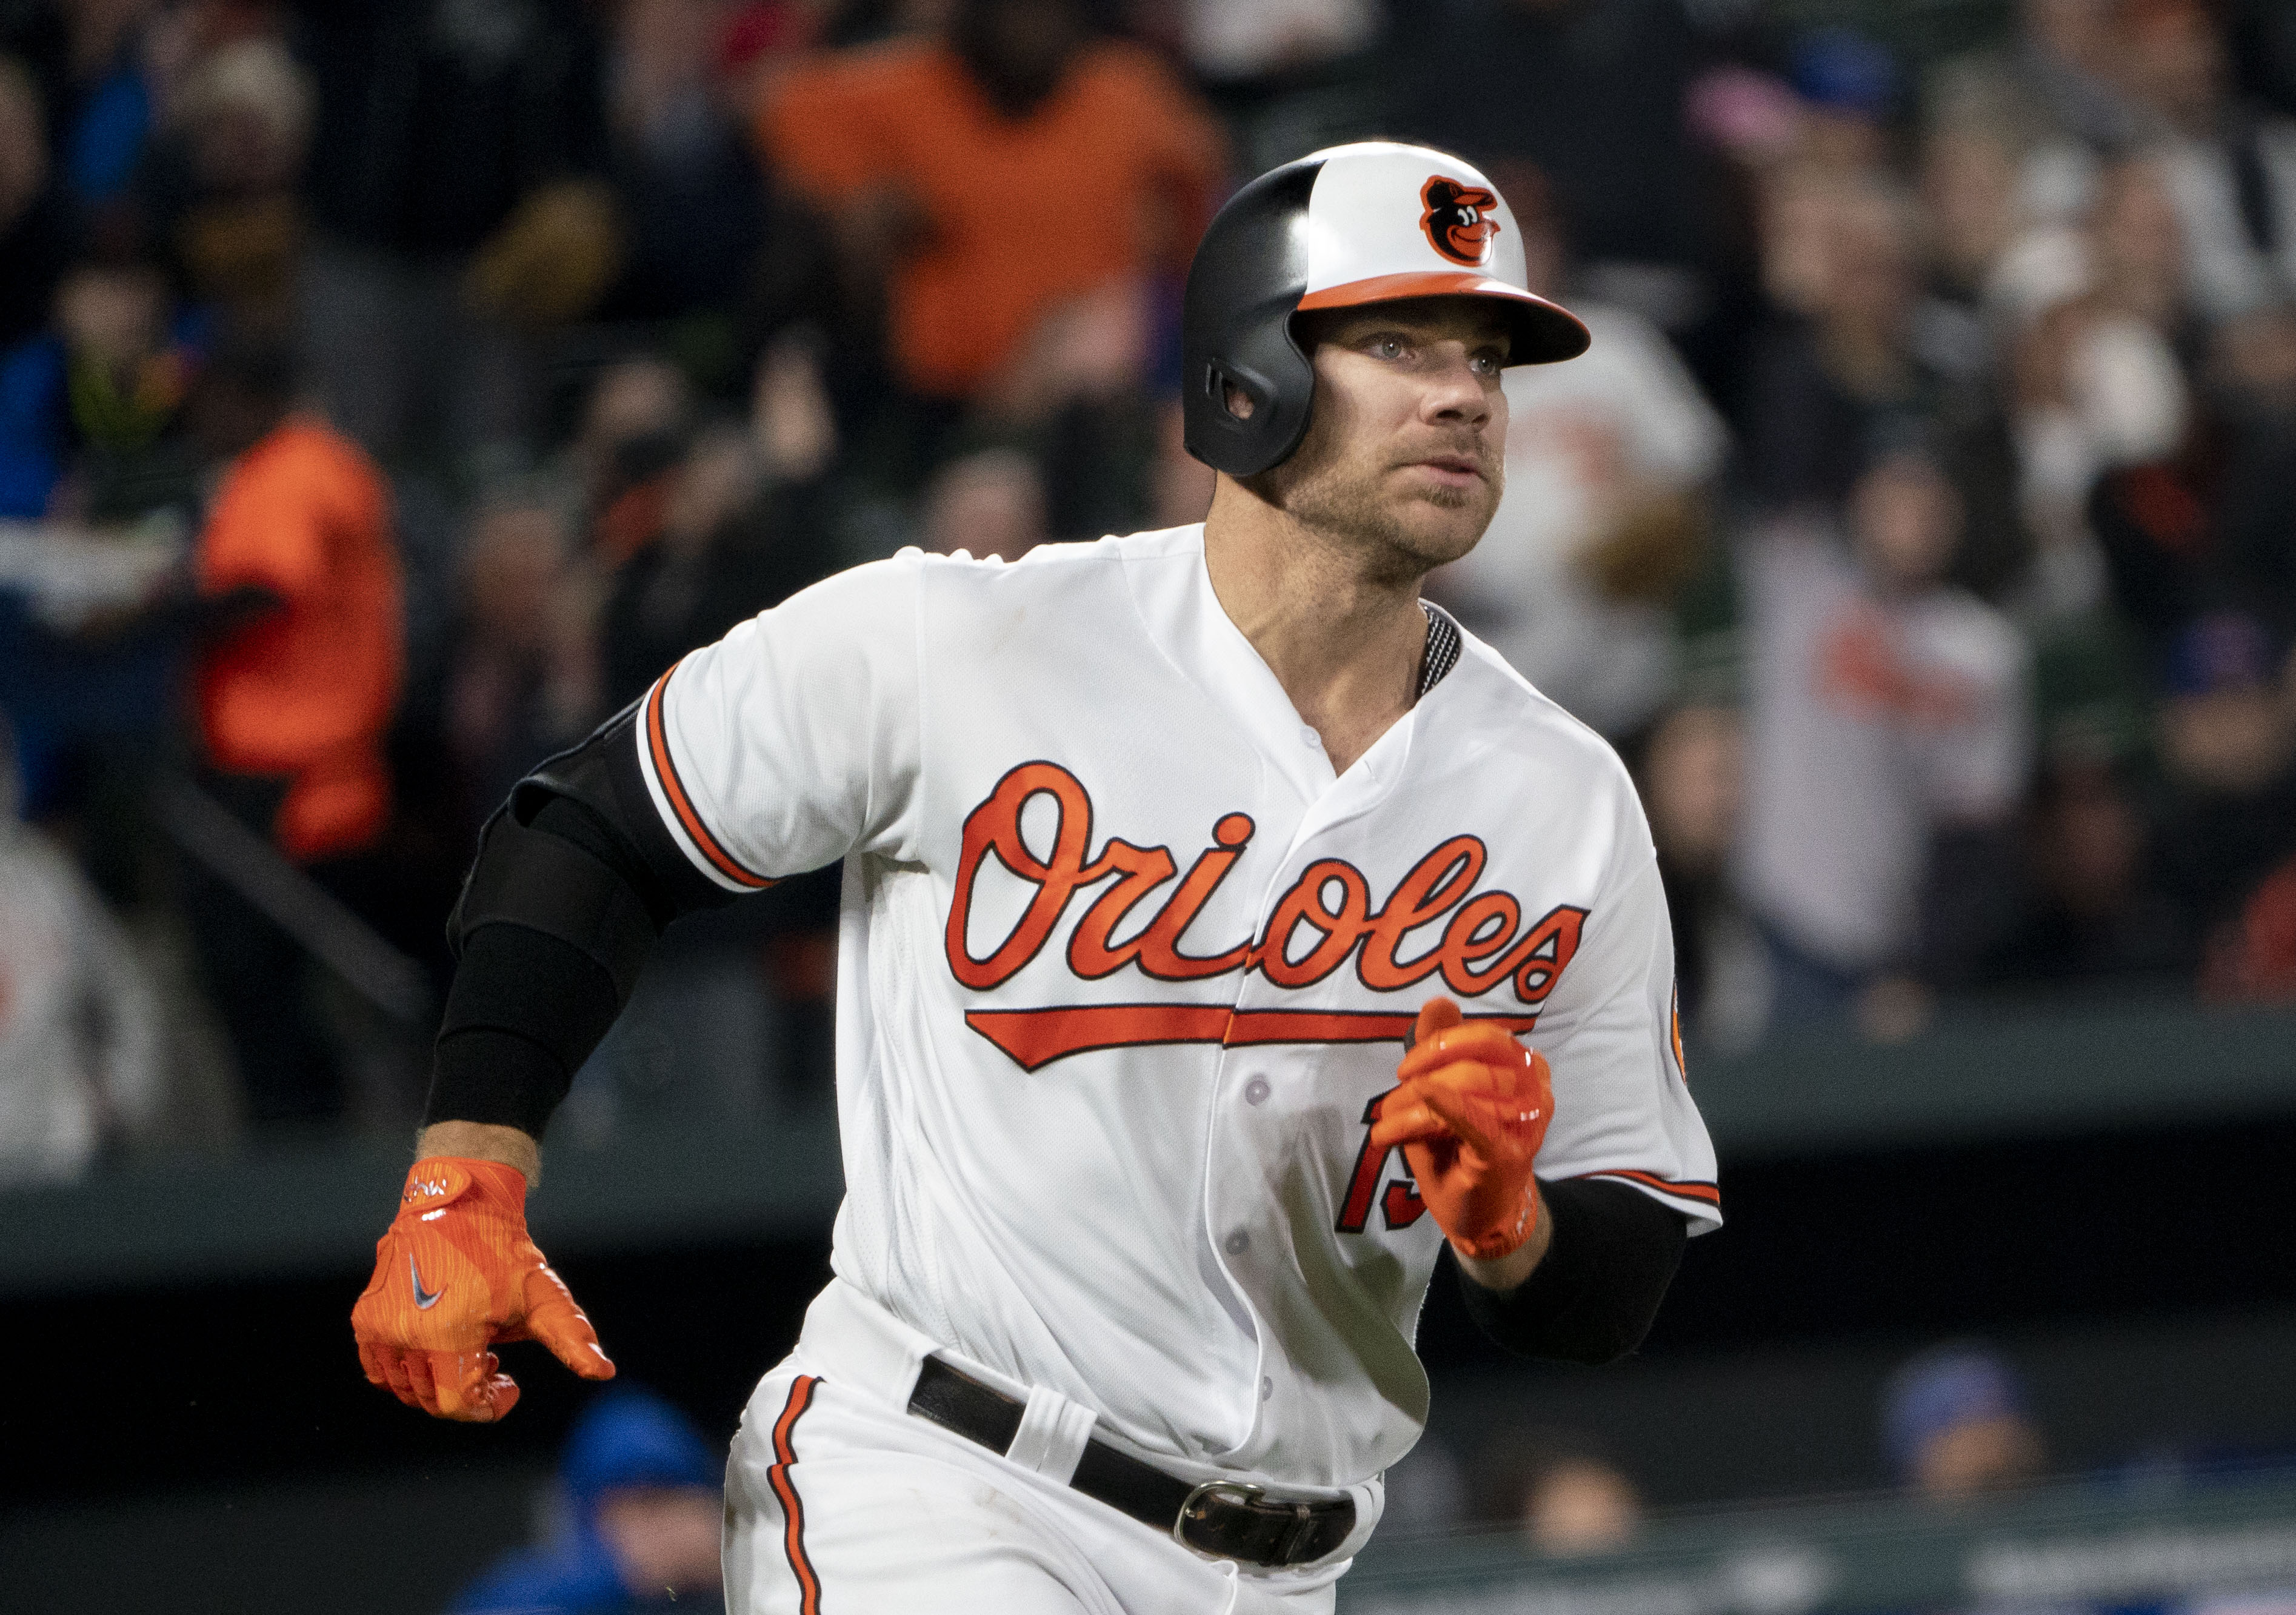
Chris Davis
American baseball player
23
APPEARANCES
20
PODCASTS
Oct 16, 2026

Chris DavisGUEST
Well, I mean, I certainly think it's an enormously riskier position than it's ever been.
Chris DavisGUEST
And they fail to recognize that the world around it can change in reaction to it working.
9 MINS LATER

speaker_1ADVERTISER
Need a hiring hero? This is a job for Indeed Sponsored Jobs.

Chris DavisGUEST
Well, I mean, I certainly think it's an enormously riskier position than it's ever been.
Chris DavisGUEST
You know, you say you get in more trouble with a good premise than a bad premise.
Chris DavisGUEST
And they... fail to recognize that the world around it can change in reaction to it working.
9 MINS LATER

Chris DavisGUEST
Well, I mean, I certainly think it's an enormously riskier position than it's ever been.
Chris DavisGUEST
And they fail to recognize that the world around it can change in reaction to it working.
9 MINS LATER
22:22
Can you walk us through how that works and how that has helped you not to leave an idea?


Kate Archer-KentHOST
So as you look at Green Bay, about four years of using a Flock product, what have you found as you look back, um, on, on this system and, and what it has done for your department?
Chris DavisGUEST
And, you know, we have lots of examples of cases that we've been able to solve that we would not have been able to solve any other way, and lots of examples of cases where we've, we've developed actionable leads much more quickly than we would have in the past without this technology.
Chris DavisGUEST
Uh, so, you know, the, the crime reduction and our crime rate has gone down over the la- since 2022.
Chris DavisGUEST
And all of the measures that we look at for crime, whether it's reported crime rates cr- overall, uh, we also look at some specific gun violence metrics that have gone down.
Chris DavisGUEST
And, you know, you can't look at one piece of technology and say that's the cause, but I think that is part of how we got to where we got in terms of making the city safer.
Kate Archer-KentHOST
Are there instances where you've chosen to prioritize people's privacy over the power of your police force?

Chris DavisGUEST
We were, we were in two different places, and, um, Tommy had started a World Series game the year before, um, and I thought was very much in the mix for the Rangers, who ended up going back to the World Series again year in 2010.
Chris DavisGUEST
I was on the taxi squad, which basically means I was suiting up to sit there and watch the game, but I wasn't avail- available unless somebody got hurt or, um, something like that happened.
Chris DavisGUEST
So, um, I was grateful to be there and to get to experience that environment, but it was really hard to sit there and watch the team that you had been with for the last couple of years, that you had, um, had some success with, um, go out and compete in the World Series and not get a chance to, to be a part of that.
7 MINS LATER

Steve MelewskiHOST
In your mind, what happened at the end, and is it just an anecdote, uh, you, you just flush it away, or is it part of a bigger resume?

Steve MelewskiHOST
Now, Chris, you noted in 23 when you came back for Adam Jones, jersey retirement you aren't sure how the reception was going to go and it went great because the fans more remembered the good times than the ending how do you sort all that out now what when your mind what happened at the end and is it just an anecdote you just flush it away or is it part of a bigger resume
Chris DavisGUEST
Yeah, it's definitely I definitely don't flush it away because it really helps me appreciate the earlier years.
Chris DavisGUEST
And I think it also kind of helps me stay grounded because the struggle was it was so prolonged.
8 MINS LATER


Ryan RipkenHOST
For the, the struggles to get to the big leagues, to the struggles at the end, for those that, that don't get that, is there a way that you could explain the difference between the two?
Chris DavisGUEST
I think, um, struggling at the beginning when you're still trying to prove yourself, there's still something that motivates you to go out there and do it every day, and really try to figure it out.
Chris DavisGUEST
And I think once you figure it out and you have success, the goal is to s- to sustain that success.
Chris DavisGUEST
And that, to me, was the hardest part because of injuries and just your body breaks down.
Chris DavisGUEST
And, um, and I think that was really what happened towards the end of my career.
15 MINS LATER
Ryan RipkenHOST
Do you mind just touching on the impact of, of those programs, uh, there here in Baltimore?
Ryan RipkenHOST
Do you mind just touching on the impact of those programs there here in Baltimore?
Chris DavisGUEST
Yeah, and I really appreciate you bringing it up because it is something that means a great deal to us.
Chris DavisGUEST
One of the things when Jill and I were traded up to Baltimore that we sat down and talked about, and this is before we had kids, was we want to get involved.
Chris DavisGUEST
like we want to get involved we want to be a part of the community um it's important to me i think it should be important to players in the game to use the platform that you have um and and there's no better place to start than in your your city's your team's hometown um so for me it was where can i find opportunities and we did christian youth athletics we did casey cares we did a number of things i think baltimore food bank jill did that with some of the ravens wives We did a number of things, but it was Brian Roberts who introduced me to the children's hospital.
Chris DavisGUEST
It's really hard to go in there and be around those kids and those families and not just fall in love with them and want to do anything you can to help them out.
Ryan RipkenHOST
Now for the fun parts here, Chris, you've had a lot of moments here in Baltimore, right? You ought to give me a couple of your favorites specifically.


Alexia KellyHOST
Chris Davis, who was a senior sustainability executive at Amazon and now serves as the interim executive director of the Task Force for Corporate Action Transparency, put it clearly.
Chris DavisGUEST
So we've been left in this situation where the policy framework, so to speak, simply can't keep up with what the companies are doing.


Chuck JaffeHOST
Before we get too far into that, give us your overarching case on how you are approaching and you think investors should be approaching AI, and then we'll get to those categories.
Chris DavisGUEST
One of the great things about having, in a sense, this long family memory, going back to my grandfather starting to invest in the 40s, is the idea that we've gone through revolutions.
Chris DavisGUEST
And of course, as students of history, we can see other technological revolutions all the way back from the printing press, through the industrial revolution, through electrification, through the electronic age, the internet age, nuclear age.
Chris DavisGUEST
And Amara's Law says that these dramatic, disruptive new technologies tend to get overestimated in the short term and then underestimated in the long term.
Chuck JaffeHOST
The walking dead is a category that you make the point that a lot of people are going to have more exposure to than they think they have or than they want to have because so much money is invested passively.


Kelly EvansHOST
Could, would you apply that to the memory stocks, to the AI infrastructure needs, or are you talking more about kind of the, the front i- facing things like an open AI Anthropic?
Chris DavisGUEST
Well, certainly the model builders are where the most risk is and the most attention.
Chris DavisGUEST
And the reason is people have, are assuming that it will be a winner-take-all model.
Chris DavisGUEST
You think of Metcalfe's law, right, where you get an early lead and you build out a telephone network, uh, or a social network, and it is a winner-take-all business.
Chris DavisGUEST
But remember, a lot of the most important innovations in history were not like that.
Kelly EvansHOST
In those episodes, when you say the, the real benefits went to the users, what, what are the stock market implications of that?
Chris DavisGUEST
Well, I think a- what I would do is I would say, well, let's, let's look at the idea that intelligence is very likely to become a utility, right? Something that is widely available.


Barry RitholtzHOST
What key investment principles stand out as absolutely core, non-negotiable, this is the heart of what we do?
Chris DavisGUEST
Well, the entire investment process boils down to these two questions: what, what sort of businesses do we wanna own, and how much do we pay for them? And it, you know, the types of business characteristics that are, that we focus...
Chris DavisGUEST
But, and the interpl- I should say before I go on that the interplay between those two is part of the nuance of investing.
Chris DavisGUEST
You may own a slightly lower quality business because it, the price is so extreme.
Chris DavisGUEST
Uh, but the characteristics that we look for in every business have to do with the durability, because we buy businesses thinking we will, our goal is to own it forever.
Chris DavisGUEST
Our goal is for the return to be driven by the yield, earnings yield on the business over time, not by some change in the valuation and finding an exit strategy.
Chris DavisGUEST
Um, and so those sorts of characteristics are exactly the characteristics you would look for if I said you've gotta put a business away for your kids or your grandkids.
15 MINS LATER


Alex ShahidiHOST
Would you just share the history of your grandfather and your father founding Davis Advisors?
Chris DavisGUEST
Well, my grandfather, very much like me, didn't start out thinking investing was for him.
Chris DavisGUEST
By the way, as had his wife, they met in graduate school, both doing PhDs in 1928.
Chris DavisGUEST
In the same way I was interested in intelligence, they were interested in global affairs.
35 MINS LATER
Alex ShahidiHOST
You touched on this a little bit earlier, but how do you think about stewardship when people are trusting you with their life savings rather than just capital on a spreadsheet?


Chris DavisGUEST
Well, I, I think that financials have this characteristic of, of where y- you get enormous sort of durability in the business model, and they're businesses where culture can be a defining business over ... a defining advantage over a, a long period of time.
Chris DavisGUEST
And I think what's happened is the financial crisis created this sense that financials are very fragile.
Chris DavisGUEST
And so capital ratios have been built, regulation has been added, just like happened after the crash and the Depression in the '30s.
Chris DavisGUEST
So you now have very durable businesses that are well-capitalized, and yet people still trade them as if they're very fragile.
Chris DavisGUEST
So I think that what will happen over the next decade is people will come to recognize that this is misunderstood durability and that they, in a sense, have the ability to grow their dividends for decades.
Chris DavisGUEST
And I think they'll go from being perceived as fragile to being perceived as boring.
Jack ForehandHOST
I mean, do you think there's something different today, like in terms of structure that, that leads to the market absorbing risk in different ways?
Chris DavisGUEST
Well, you know, I certainly think that there has been an increasing view that speculators will be bailed out.
Chris DavisGUEST
And you know, I, I went to, uh, I, I recently visited, there was a wonderful judge, Judge Patterson.
Chris DavisGUEST
He lived in the Hudson Valley, and, and I think I'm remembering this right, uh, that one of h- uh, when he was a very old man, he, uh, was, uh, brought into, uh, review and, uh, uh, he was the judge on some of the cases that were brought against the big wire so- wirehouse firms for, uh, by little old ladies that had invested in, uh, hot tech IPOs in 1999.
Chris DavisGUEST
You know, you know, I should never have been bought this, and I..." And his opinion said, "It is not the job of the judiciary to indemnify speculation." Right? Which was a wonderful...
Chris DavisGUEST
Nobody bought, you know, it, it, nobody bought a, a tech IPO, uh, uh, thinking that they were buying DuPont, right? They knew, and they want the upside, but they wanted, you know, the, the wirehouse to take the downside.
Jack ForehandHOST
So could you just talk about like how you're thinking about AI as an investor in general?


Chris DavisGUEST
Each of us has our – calling card yeah like has our thing you know like i i had the power mitch was like a better all-around hitter justin had a better eye like we all had our thing um but it's like we're kind of like looking at each other and we all loved each other and cared about each other i mean we we played with each other in the minor leagues and we all wanted each other to do well but at the same time it's like it's gonna be either it's either gonna be me or you guys And so I think when he got traded, and it wasn't like a get him out of here, like get him out of my way.
30 MINS LATER

Chris DavisGUEST
We actually put every company we look at through a lens, uh, of, of how AI may, uh, impact their business, and we actually have five categories that we touch on.
Chris DavisGUEST
You know, one is, who are the emerging winners? That's where all the time is spent.
Chris DavisGUEST
There were three surefire winners of the internet, and, uh, it was Cisco, Yahoo! and AOL, right? So it's very dangerous early in a mega trend in a new technology to imagine you're picking the winners.
11 MINS LATER

Nate GeraciHOST
And so what do you think are the right questions for investors to ask when looking at their options? Does it ultimately come down to performance, whi-which we were just talking about, or how should they think about this?

Chris DavisGUEST
Well, you know, I think this is where all of our experience and my gray hair sort of helped because we've seen this before.
Chris DavisGUEST
It really, you know, just in the history of our funds, you know, we saw an enormous growth cycle that culminated in the nifty 50 in 1972 and then marked the beginning of a long trading range of market.
Chris DavisGUEST
But, you know, in those galloping periods of time when there's optimism prevails, value discipline gets pushed aside, multiples expand, it tends to be a time when value investing can get left behind and there begins to be talk of a new, new era.
29 MINS LATER

Andrew BaryGUEST
I mean, do you know, what would you characterize as the company's biggest challenge right now at first?

speaker_7UNKNOWN
Now he's back.
Chris DavisGUEST
Uh, and, uh, uh, and, you know, everything about globalization versus national, you know, uh, it, all of that is becoming unwound in a way that we don't know how it will play out, but it is a massive shift and it will shift supply chains, it'll shift margins, productivity, inventories, all sorts of things.
Chris DavisGUEST
Third transition is, of course, we are in what will be the greatest transition probably since the Industrial Revolution, of course with AI, and, and it's, it, it...
18 MINS LATER


Mike SantoliCORRESPONDENT
From your perspective as an investor, Has it caused you to reassess the broad outlook or the market you think we're in? Or has it created any opportunities?
Chris DavisGUEST
Well, I think we came into this year with three big transitions happening simultaneously.
Chris DavisGUEST
So you had this enormous change in sort of the monetary background of the economy.
Chris DavisGUEST
We had 15 years of near zero interest rates, free capital, magical thinking, modern monetary theory, deficits don't matter, all of that.
Chris DavisGUEST
Then we've had this enormous geopolitical change, the end of globalization, the breakdown of a sort of stable world order.
Mike SantoliCORRESPONDENT
Just from your perspective, I know you're not going to get ahead of Warren tomorrow and talk too much about what's going on with the business, but as an investor, what does an investor own from now and into the future when they own Berkshire Hathaway? Obviously, there's going to be this transition at some point into new leadership, but what is the business?

Chris DavisGUEST
You gotta give me something." And so I'm kind of pushing him, nudging him a little bit and-
29 MINS LATER

Lester HoltHOST
But once the reality set in, other questions started bubbling up about Natalie and about Michael's death.
Chris DavisGUEST
Once you get away from that initial shock, you start putting the puzzle pieces together.
Kelly EvansHOST
Let me just take a step back, Chris, and ask, I mean, what do you think is going on with the market here? And do you need to have kind of a grand theory of everything? Or are you kind of just keeping your head down and looking for stock by stock opportunities?
Chris DavisGUEST
Well, I think the grand theory you have to have is that we came into this year with three massive transitions happening at the same time.
Kelly EvansHOST
So with the shock in business confidence we've seen, by some estimates, it's the worst since know 15 years 20 years i mean it the collapses in the isms the outlooks that sort of thing so and we've had earnings estimates which already started to stall out especially for big tech all the way back in june have we reached the worst of this now where you think things can drop and look better maybe we have to get through the next earnings season you know before that how much more bad news do you think there is before we start to turn a corner here

Chris DavisGUEST
Well, of course, the pattern of cash flows, the farther out a payment is, the less it is worth today.
6 MINS LATER

Andy SerwerHOST
And then also wanted to ask you about Meta, which is a stock that you bought when it was sort of down and out.