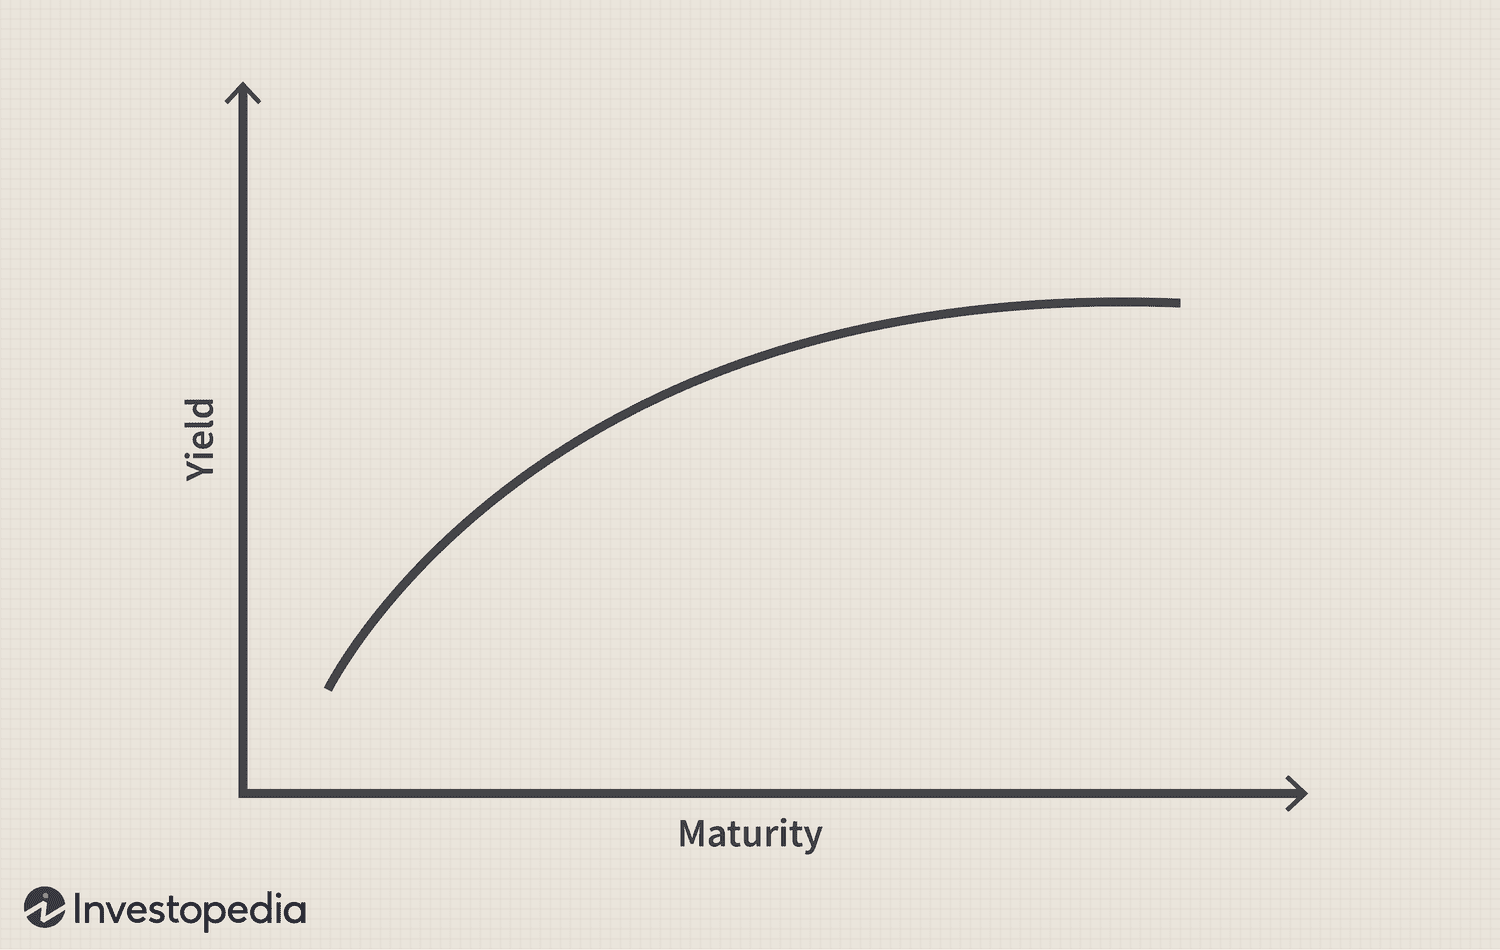
Yield curve
102
MENTIONS
32
EPISODES
28
PODCASTS
Search complete. 102 mentions across 32 episodes found for "Yield curve".
Sep 16, 2026

Bill LeeGUEST
And that is a message of unity rather than a message of dominance by any one individual.
speaker_0HOST
And Jeff, how are you looking at the yield curve right now? I mean, yesterday, part of my takeaways at the end of the day were that we had the 10-year above 5% for the first time in almost two decades.
speaker_0HOST
We had the 30-year hit a similar mark.
speaker_0HOST
That's another major financial condition issue for the Fed to address.

Trey ReikGUEST
These are all totally unprecedented events.
Trey ReikGUEST
We're moving towards yield curve control, which is essentially money printing life.
Trey ReikGUEST
This is the opportunity you've been waiting for.
Maggie LakeHOST
Hello and welcome to Wealthy on a Maggie Lake.
9 MINS LATER
Maggie LakeHOST
When Besant came out and started buying back bonds and intervening, there was a lot of uproar.
Maggie LakeHOST
Stan Druckenmiller wrote an op-ed about it.
Maggie LakeHOST
A lot of people started talking about things like yield curve control.
Maggie LakeHOST
Why are people so worried about the sort of extraordinary moves that Besant seems to be making and even whether the Fed has the right tools to address this.

Craig HemkeGUEST
I mean, the truth of the matter is they got a lot of ground just to kind of catch up to what the market's done.
Craig HemkeGUEST
Because since the war began back at the 1st of March, the entire yield curve has shifted a full 1% higher.
Craig HemkeGUEST
while Fed funds, the only rate that the Fed controls, the overnight rate, has remained exactly the same.
Craig HemkeGUEST
So, I mean, you could argue, I mean, I'd be willing to listen to the argument that Fed could raise 50 or 75 basis points just in an effort to kind of catch up with the rest of the curve, which then leaves you thinking, well, then what difference does it make if we get a 25 basis point rate hike or 50? Why would that not even be priced in at this point? Which then opens the door to, you know, more dovish interpretations, perhaps, if nothing happens.

Samantha AzzarelloHOST
Takafumi, thank you.
Samantha AzzarelloHOST
You're already speaking to it and alluding to it, but I'm going to just ask explicitly then about the long end part of the yield curve.
Samantha AzzarelloHOST
So we've seen a global repricing of term premia globally, I would say, and I know our global fixed income strategists would say that.
Samantha AzzarelloHOST
How much of the Japan story right now is Japan specific factors versus something that's maybe a little bit more global and ubiquitous in nature across fixed income markets?

DorkHOST
I'll say.
DorkHOST
What, if any, avenues are there that can stabilize the yield curve and how screwed is Besson?
Jay FreshHOST
Warsh can buy a bunch of it.
Jay FreshHOST
where Congress can stop spending some of it.

Mike WebsterGUEST
Like, they're really, really smart.
Mike WebsterGUEST
They look at every last, uh, bit of data to figure out where the rates should go, and the, the whole yield curve thing is, is something you could spend your lifetime studying and probably still have more to figure out, just like with the, with the stock market.
Mike WebsterGUEST
So it does do weird things.
Mike WebsterGUEST
Sometimes, you know, you get the, the one end going up and then the other end coming down and kind of flattening that out.
Mike WebsterGUEST
And the good thing about Bill is he, the founder of IBD, he wouldn't get down into that rabbit hole.
Mike WebsterGUEST
He would just say, "Okay, there's lots of moving parts there.
Mike WebsterGUEST
What can I do? I can just keep it simple and just look at what the S&P is doing or what the Nasdaq is doing," or whatever your favorite, um, instrument is that you're actually trading, rather than overthinking it and then just making things too complicated for yourself because then you're looking at, oh, okay, well, the fed fund futures are doing this, the, the 10-year and the 30-year are doing this, and the, and the yield curve that, you know...
Mike WebsterGUEST
And people years ago, the yield curve inverted, and everyone was, was freaking out about it.

Ian LyngenHOST
We'll argue that this is one of the factors pressuring real yields higher and adding to the recent increase in term premium.
Ian LyngenHOST
Term premium is up, that follows intuitively, and while the shape of the yield curve has flattened, not steepened as of late, the reality remains that investors need further compensation to go out the curve, and this is unlikely to change in the foreseeable future.
Ian LyngenHOST
It does build a good case for ten-year yields testing five percent, and even for the long bond renewing its cheapening trend as the real economy and risk assets continue to perform well.
Ian LyngenHOST
This suggests that the next big wild card will be whether or not stocks can survive a series of rate hikes that are designed to cool demand, put downward pressure on inflation, and presumably will lead to some recalibration of equity valuations, if nothing else.
Delaney ChoiPANELIST
And on the flip side of the bond bearish argument, even if we've seen ten and 30-year yields move back above levels that we saw immediately before Bessent announced larger buybacks, the Treasury Secretary can defend his decision to upsize bond repurchases by pointing to the outperformance of U.S. Treasuries versus most other major sovereign debt over the past several weeks.
Delaney ChoiPANELIST
Bessent can also point to the fact that ten and 30-year Treasury term premium has come down since the August 19 announcement of increased long end buybacks.
Delaney ChoiPANELIST
This term premium dynamic has been one of several key contributors to the sharp flattening of the yield curve over the past few weeks.
Delaney ChoiPANELIST
Obviously, the hawkish shift in Fed pricing and the surge in oil prices has contributed to the flattening pressure, but the market is also pricing in the structural implications of the expanded buyback program for the overall balance between supply and demand in the long end of the yield curve.

Swaha PatnaikHOST
You were talking about the structural problems, the fiscal structural problems, and also some of the problems that Mr. Walsh faces, which is more affecting the short end, perhaps.
Swaha PatnaikHOST
How have those two things over summer affected your views, perhaps, on the yield curve and where the value lies?
Monica DefendGUEST
Well, it confirms and we remain convinced about the steepening of the curve.
Monica DefendGUEST
Then the size of the movement is debatable, but when compared to the market, given our out-of-consensus call on the Fed, now the consensus aligns on the ECB, but still there back in July, we were...

Raoul PalHOST
Yeah, they're going to be pretty anchored in the end.
Raoul PalHOST
But what everybody needs is a steeper yield curve.
Raoul PalHOST
So they kind of do need the Walsh part of the equation.
Raoul PalHOST
And I think Walsh is playing the game, which is he's got to sound credible and tight.
Raoul PalHOST
I don't think it clears now.
Raoul PalHOST
I think it clears at some point down the road from the nexus of both AI and this and yield.
Raoul PalHOST
So I kind of still are looking for the weaker dollar and a steeper yield curve and just see how it goes from there.
Raoul PalHOST
And to your Japan point is...

Tim PierottiHOST
You know, is it sustained? I don't know.
Tim PierottiHOST
But man, I would not want to be dead long, the long end of the yield curve right now.
Tim PierottiHOST
Not...
Tim PierottiHOST
Not at all.
22 more episodes mention Yield curve.
Create an account to see the whole feed, search across every transcript, and follow the entities you care about.