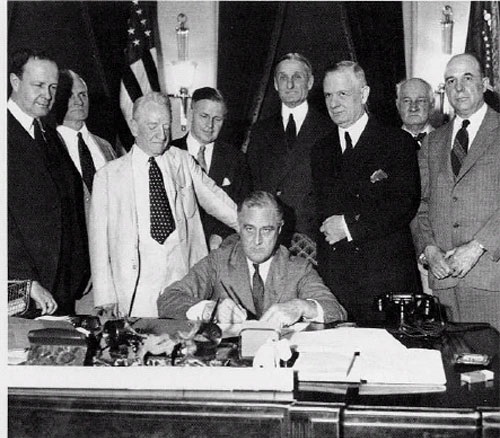
Securities Act of 1933
24
MENTIONS
16
EPISODES
14
PODCASTS
Search complete. 24 mentions across 16 episodes found for "Securities Act of 1933".
Sep 11, 2026

Phil BrownGUEST
All I did was I put all the rules and regs in there.
Phil BrownGUEST
You know, like the Securities Act is like 30, 40, 50, 60 pages or 30 pages.
Phil BrownGUEST
They put that in, they shrunk it, and then they put all the summaries and all that kind of stuff.
Phil BrownGUEST
So a lot of this, as I said, is more compilation than actually writing a book.

Rigoberto TiglaoNARRATOR
Precedent There is also a useful American precedent, the United States Senate's Pacora investigation, named after the prosecutor who led the investigations, in 1933 exposed conflicts of interest, deceptive securities practices and reckless conduct by major Wall Street institutions before the Great Depression.
Rigoberto TiglaoNARRATOR
Congress followed with the Securities Act of 1933 and Securities Exchange Act of 1934, creating the Securities and Exchange Commission.
Rigoberto TiglaoNARRATOR
An investigation became rules, disclosure and an institution intended to outlast the scandal.
Rigoberto TiglaoNARRATOR
That is the standard by which the Romualdes case should be measured.

Austin HaynesGUEST
It's not just the Telecommunications Act of 1996 that regulated something to be able to allow immense growth.
Austin HaynesGUEST
It was actually known as the Securities Act of 1933.
Austin HaynesGUEST
This document goes on to say, without clear regulation, the US regulatory approach over the last decade has distorted markets, stifled innovation, and left consumers exposed to significant harms.
Austin HaynesGUEST
Clarity would end this period.
Austin HaynesGUEST
Like the Securities Act of 1933, which established investor protections and power the century of U.S. capital formation and innovation, clarity creates a once-in-a-generation shift in the U.S. financial regulatory landscape, the kind of shift that creates enormous opportunity.
Austin HaynesGUEST
People don't realize the opportunity at hand.
Austin HaynesGUEST
People don't realize the scale at hand.
speaker_10ADVERTISER
Try Addio free at addio.com slash iHeart.

Chris JourdanHOST
The issuer is registered under the r-registration number...
Chris JourdanHOST
Stock tokens have not and will not be registered under US Securities Act of 1933 as amended from time to time, the Securities Act, or with any securities regulatory authority o-of any state or other jurisdiction in the US.
Chris JourdanHOST
Stock tokens may not be offered, sold or delivered within the United States to or for the account or benefit of US persons as defined in the Brit-...
Chris JourdanHOST
He goes on to read the rest basically copied and pasted from their docs.

speaker_2NARRATOR
The information contained in this podcast is believed to be reliable, but RBC Blue Bay cannot and does not guarantee its accuracy, timeliness or completeness.
speaker_2NARRATOR
The document is intended only for professional clients and eligible counterparties as defined by the Markets and Financial Instruments Directive or in the US by accredited investors as defined in the Securities Act of 1933 or qualified purchasers as defined in the Investment Company Act of 1940 as applicable and should not be relied upon by any other category of consumer.
speaker_2NARRATOR
No part of this document may be reproduced, redistributed or passed on directly or indirectly to any other person or published in whole or in part, for any purpose, in any manner, without the prior written permission of RBC Blue Bay or one of its entities.

Ran ChenHOST
Due diligence is the underwriter's legal obligation to thoroughly investigate the issuer's business and the accuracy of the registration statement.
Ran ChenHOST
This is their primary defense against liability under the Securities Act of 1933.
Ran ChenHOST
Finally, you must understand conflicts of interest.
Ran ChenHOST
Under FINRA Rule 5121, if a broker-dealer is underwriting its own securities or those of an affiliate, a conflict exists.

Jacob RobinsonHOST
I found it helpful just mapping the president's working group's recommendations to the initiatives that we've seen so far from the SEC, particularly when it came to red crypto.
Jacob RobinsonHOST
I thought it mapped pretty nicely onto what they had sort of recommended the SEC do when it came to the Securities Act.
Jacob RobinsonHOST
One thing I found interesting, though, was that the working group's third recommendation relating to the 33 Act told the SEC to, quote, consider an exemption for D-PIN providers distributing tokens to network to reward network participation.
Jacob RobinsonHOST
The startup exemption covers network rewards generally, and we've seen with the March guidance things on airdrops, but nothing's been D-PIN specific.
Jacob RobinsonHOST
And that was important because that group was ordered to report back with recommendations, and they did that six months later.
Jacob RobinsonHOST
This report included a list of immediate actions that the SEC should take under the Securities Act.
Jacob RobinsonHOST
And these three recommendations will sound familiar because it's what they did.
Jacob RobinsonHOST
It's establish a fit-for-purpose exemption from registration for digital asset distributions.
46 MINS LATER
Lewis CohenSOUNDBITE_SPEAKER
I don't have any beef with that whatsoever.
Lewis CohenSOUNDBITE_SPEAKER
The concern I have is its impact on others.
Lewis CohenSOUNDBITE_SPEAKER
Because the point of Form TR is not only to protect the issuer entity from knowing when they have ceased engaging in securities activity, but third parties, E&C in my example, and how they know.
Lewis CohenSOUNDBITE_SPEAKER
So if it turns out that you're a, for example, a dealer or a market participant or someone who might have securities law obligations, if these all were securities transactions, you see the form TR being filed, you're like, hmm, way to go, I'm in, right? And yet, and yet, it may turn out subsequently, unbeknownst to you, that the issuer either intentionally or maybe inadvertently misrepresented.

Simon TaylorHOST
The idea here is that startups can raise sales.
Simon TaylorHOST
$5 million exempt from Securities Act registration for four years, and larger raises get up to $75 million for one year.
Simon TaylorHOST
And the key part is this.
Simon TaylorHOST
Safe Harbor lets a digital asset stop being a security once the issuer has ceased all managerial assets.

Alex ThornGUEST
But I think, like, the commission acting here is trying to fulfill what they promised, which is that there's gonna be market clarity on crypto, whether it's primary issuance or secondary trading, regardless of what Congress does.
Alex ThornGUEST
I think the, the reg crypto is probably more legally defensible, um, given that, like, you're talking about issuing securities effectively, and they do clearly have the sense of Congress under the Securities Act to, to regulate that.
Alex ThornGUEST
Innovation exemption, um, also decent.
Alex ThornGUEST
I think the one that's really tricky for the agencies in terms of, like how they're, whe- whether their rulemaking can be durable and have fidelity, for example, against lawsuits, especially under Lapper Bright, is the prediction markets question i- for the CFTC, where, you know, Chair Selig has been very bullish on defending his agency's jurisdiction over prediction market event trading because they're swaps.
6 more episodes mention Securities Act of 1933.
Create an account to see the whole feed, search across every transcript, and follow the entities you care about.