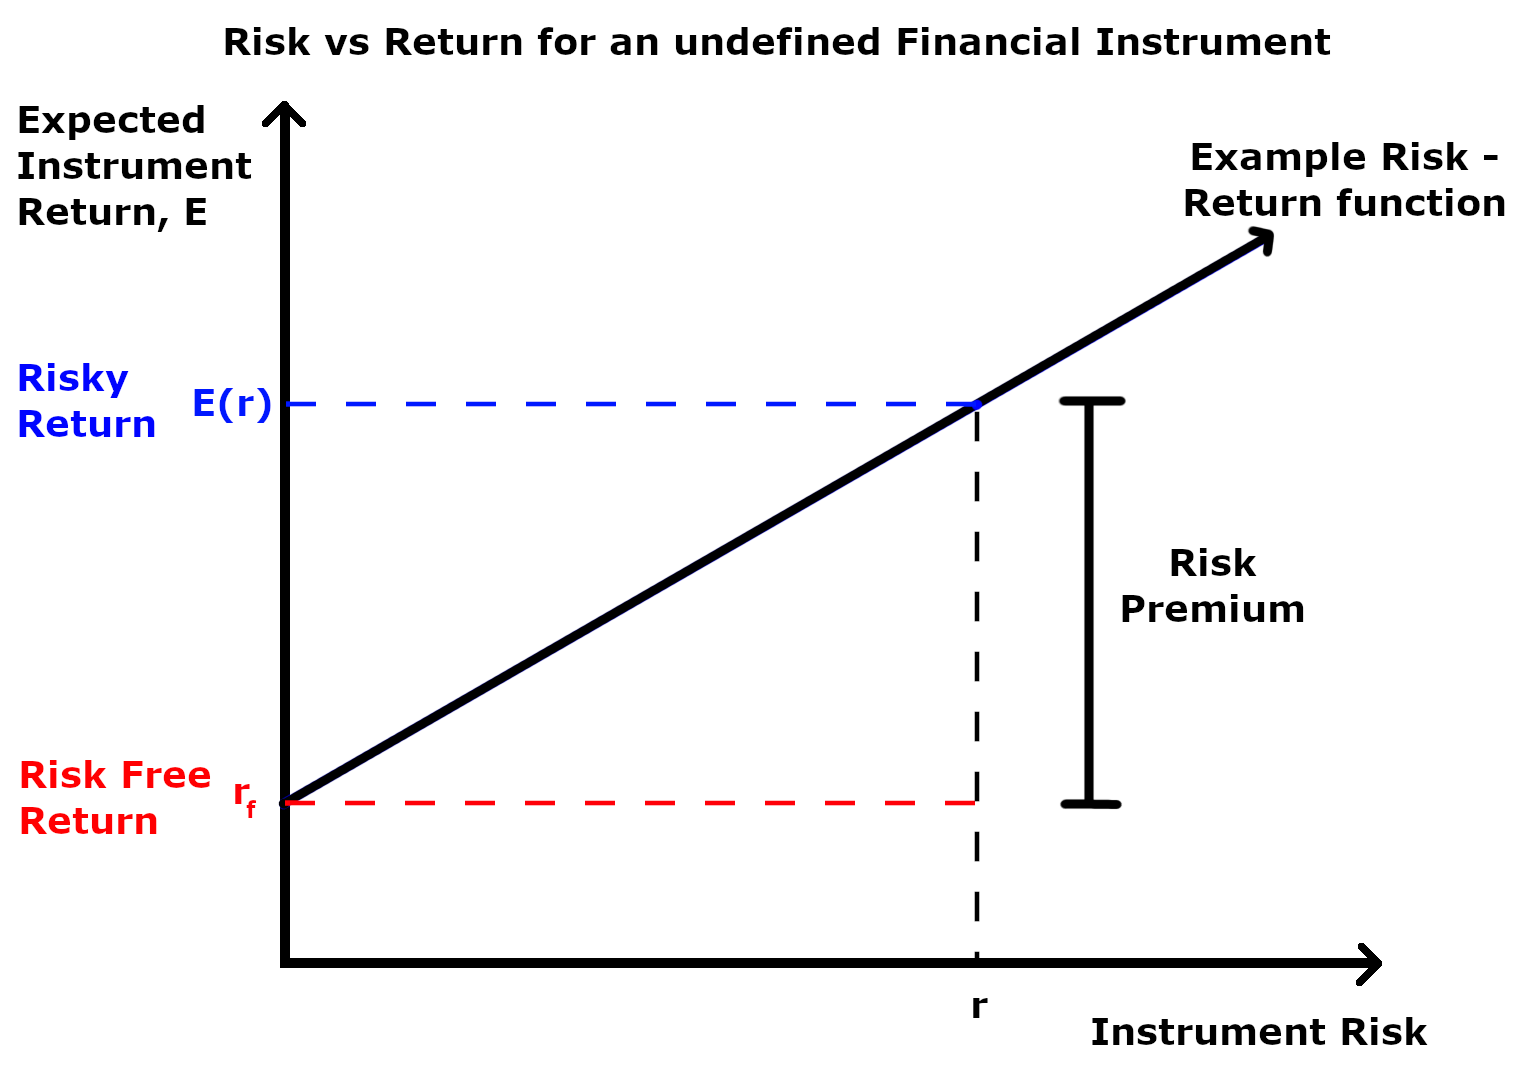
Risk premium
24
MENTIONS
5
EPISODES
4
PODCASTS
Search complete. 24 mentions across 5 episodes found for "Risk premium".
Sep 16, 2026

Ermengarde JabirGUEST
We'll leave those aside for the moment because there's so many other dynamics happening in the office sector.
Ermengarde JabirGUEST
um but you know if you think about cap rates for uh industrial sort of in the sixes generally speaking um you know data center cap rates are more competitive they're generally speaking lower which is good for data centers but of course there's always a bit of a niggle in terms of where the 10-year treasury yield stands you know we've seen it really pushing up um more recently you know beyond four four and a half percent to 4.6 4.7 and so you know there's always the consideration of uh the shrinking risk premium um you know certainly i'm a big fan of all cre i think i've said this before on the show um but cre as wonderful as it is it is not you know a risk-free asset And so, you know, there's always that consideration when you start to get a risk premium that is shrinking where the cap rate is so close to the risk-free rate it doesn't really allow for a lot of wiggle room.
Michael BullHOST
Let's talk about adaptive reuse.
Michael BullHOST
I know some folks have done some conversions, right, of office properties or retail properties?

Kimberly GallantGUEST
That's a really interesting example.
Kimberly GallantGUEST
So over time, harvesting the volatility risk premia in QIS format has evolved.
Kimberly GallantGUEST
And so it actually, the first strategies I was aware of, well, the first were probably the VIX roll trade.
Kimberly GallantGUEST
Then it evolved into delta hedged straddles or strangles.
Kimberly GallantGUEST
And the banks had the technology from when we were doing the original Delta hedge straddles to deliver instead a portfolio of options.
Kimberly GallantGUEST
So that's when it did converge to.
Kimberly GallantGUEST
And today, the most common VRP applications for just a very vanilla, how do I harvest the volatility risk premia in equities would be, for example, to sell on a daily basis a strip of options that are expiring in a week.
Kimberly GallantGUEST
That would be the one over K squared variance replication portfolio.

speaker_0NARRATOR
SFM Market Update with Jimmy Muyaha.
Jimmy MoyahaHOST
For many years, the risk premium associated with the United States has almost been non-existent, but of late, as of the last 18, 19 months or so, that risk profile starts to look very, very different.
Jimmy MoyahaHOST
I thought we'd take a deeper look at this in light of some recent events that I found particularly interesting.
Jimmy MoyahaHOST
I'm joined on the line by Chief Economist at PSG Financial Services, Johan Els, to see if he can help me unpack this.
8 MINS LATER
Johan ElsGUEST
All of that should help the economy and confidence amongst investors, consumers and businesses.
Jimmy MoyahaHOST
And confidence is exactly what we need for attracting investments and retaining those investments.
Jimmy MoyahaHOST
We'll see whether or not the risk premium on the United States continues to rise and how it is that the markets respond to that.
Jimmy MoyahaHOST
For now, we'll leave the conversation on that note.

Aswath DamodaranHOST
You're setting a price for risk in the equity market, the equity risk premium, you set a price of risk in the bond market, it's a default spread.
Aswath DamodaranHOST
Most of the time, the two move together.
Aswath DamodaranHOST
What do I mean by that? If people get scared, there's a crisis, both equity risk premiums and default spreads go up.
Aswath DamodaranHOST
If you're feeling really good, the price of risk in both markets comes down.
Aswath DamodaranHOST
But there have been periods, especially in the last 25 years, where the two have moved in opposite directions.
Aswath DamodaranHOST
All that will happen is you multiply it.
Aswath DamodaranHOST
You need a risk-free rate, you need a beta of betas, and you need equity risk premiums.
Aswath DamodaranHOST
just without even looking at the numbers, which of these should be the most straightforward of the three numbers to get,
Hunter HarrisADVERTISER
you think?
28 MINS LATER
Aswath DamodaranHOST
When that goes, that crutch is now gone, right? I can't say there's one ratings agency that gets to...
Aswath DamodaranHOST
Then I have no choice but to adjust for it.
Aswath DamodaranHOST
For me, it's a little bit of a nightmare because so many of my risk premiums start with the U.S. equity risk premium But it's actually a mechanical adjustment where you have to adjust for the fact that you now have default spread in what you used to call your mature market base.
Aswath DamodaranHOST
But it's doable.